Cave de Genève
By Anthony Lebrun
There is a stubborn misconception in business: that size equals power. Large companies are assumed to enjoy the resources, brands, networks and economies of scale that give them an automatic edge over smaller rivals.
There is some truth in this in volume-driven markets. But it overlooks a basic principle of competition: once customer needs become specific, relevance beats scale. And customers’ needs, whether they are companies, institutions or private individuals, are rarely as standardised as large organisations like to think. A client who needs a bespoke solution, a rapid response to a complex situation, or someone who understands their sector in fine detail will not necessarily be best served by a broad-based provider whose offering was designed for the greatest number. That is precisely where SMEs thrive, and they do so on four fronts.
The first is responsiveness. A client facing an urgent or unusual situation does not need an 18-step process and four layers of sign-off. They need someone who grasps the problem straight away and can act on it. In an SME, the decision-maker is usually a phone call away. The chain of command is short, and that brevity has real economic value for clients whose problems cannot wait.
The second is customisation, where SMEs hold a structural advantage. Large groups standardise not for lack of ambition but out of economic necessity. Profitability at scale depends on an offering that can be replicated, processes that are documented and staff who can cover for one another without any drop in quality. This industrial logic delivers efficiency, but it also breeds a certain indifference to the individual client. Yet clients, be they companies, institutions or high-net-worth individuals, rarely fit neatly into predefined boxes. They know it and accept it up to a point, but they expect their provider to recognise the gap and address it rather than pretend it isn’t there. An SME can afford to treat every engagement as a special case. It does so not because it lacks method, but because it knows its craft well enough to depart from the standard without losing rigour. What separates amateur improvisation from genuine bespoke work is not how far the offering is tailored, but the expertise that makes the tailoring possible.
Against large groups, SMEs have weapons their competitors cannot buy
Proximity, the third advantage, is probably the most misunderstood. It is too often reduced to geography: the local firm that knows the area, can be there in 30 minutes and will be on site first thing the next morning if something goes wrong. That kind of proximity exists, and it matters, particularly in markets where trust is built slowly and face to face. But the proximity that really counts is of another kind. It is sectoral, cultural and, in a professional sense, linguistic. An SME that specialises in a given industry shares with its clients a vocabulary and a set of unspoken references. It understands the regulatory constraints, internal tensions and reputational stakes that shape their daily reality. That shared understanding is worth more than any price tag. It cuts the time spent explaining context, removes basic misunderstandings and speeds up delivery. Above all, it creates a relationship in which clients feel understood rather than merely served. Large generalists can mimic this on the surface. They cannot reproduce it in depth, because it comes from immersion, not training.
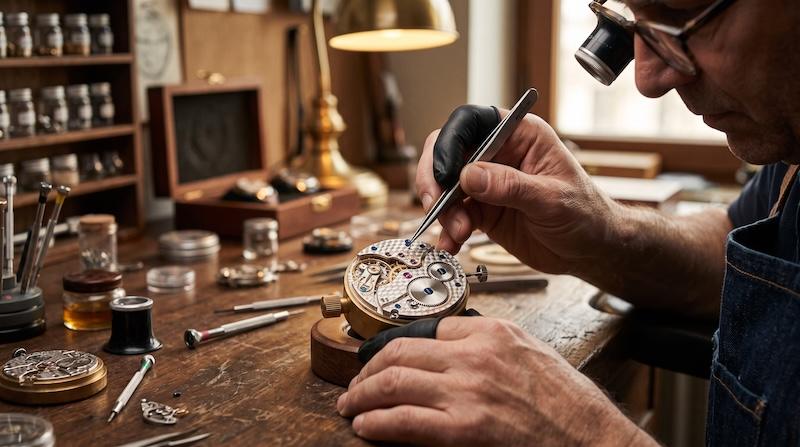
The fourth advantage, specialisation, is the most powerful lever available to ambitious SMEs, and the least used. Choosing to master a narrow, demanding segment rather than cover a broad but shallow one is an uncomfortable decision. It means passing up visible opportunities to build a position that will stay invisible for some time. Over the medium term, however, the effects are remarkable. An SME that takes its specialisation to maturity reaches a position competitors struggle to replicate. It becomes the benchmark in its field, not by claiming the title but by proving it time and again. In the end it has no real direct competitors, having carved out a space so precisely its own that nobody else occupies quite the same ground. “Niche” is often used dismissively. Strategically, it is a compliment, and it can lead to a kind of soft monopoly: clients who need what the firm does simply cannot ignore it.
These four advantages should be seen for what they are. They are not innate virtues that SMEs possess by nature. They are strategic choices, built on solid expertise and sustained over time. Without that foundation, each one backfires. Responsiveness without mastery turns into haste. Customisation without rigour becomes costly improvisation. Proximity without substance is mere familiarity. Specialisation without real depth is a niche story that fails to deliver. Expertise is what turns the structural features of a small business into real, defensible and lasting advantages over far better-resourced rivals.
Large companies have known this for a long time, even if they rarely say so openly. In many sectors, growth by acquiring SMEs is a deliberate strategy: big groups buy what they cannot build. What they are buying is a combination of deep know-how, operational agility and sector reputation that takes years to establish and cannot be conjured up by a management decision. When an industrial group such as Schneider Electric buys a specialist engineering firm, it is not the target’s size that attracts it. On the contrary, it is the very smallness of the business and everything that comes with it: concentrated expertise, close client relationships and a reputation that cannot be replaced. Acquisition is the sincerest form of competitive recognition.
This shift in perspective may be the most useful thing this report can offer SME leaders who sometimes doubt their ability to stand up to the giants in their sector. The question is not whether you can compete with the big players. In your own field, the one you have chosen with precision, built with consistency and defended with conviction, the question does not even arise. There, you are not competing with them. You are simply the one to beat.
A client who needs a bespoke solution or a rapid response will not necessarily be best served by a provider whose offering was designed for the greatest number
Find all our Analysis articles